
- US stocks entered the fourth quarter under pressure from rising Treasury yields, while technology shares showed relative resilience and investors reassessed the Federal Reserve's next move.
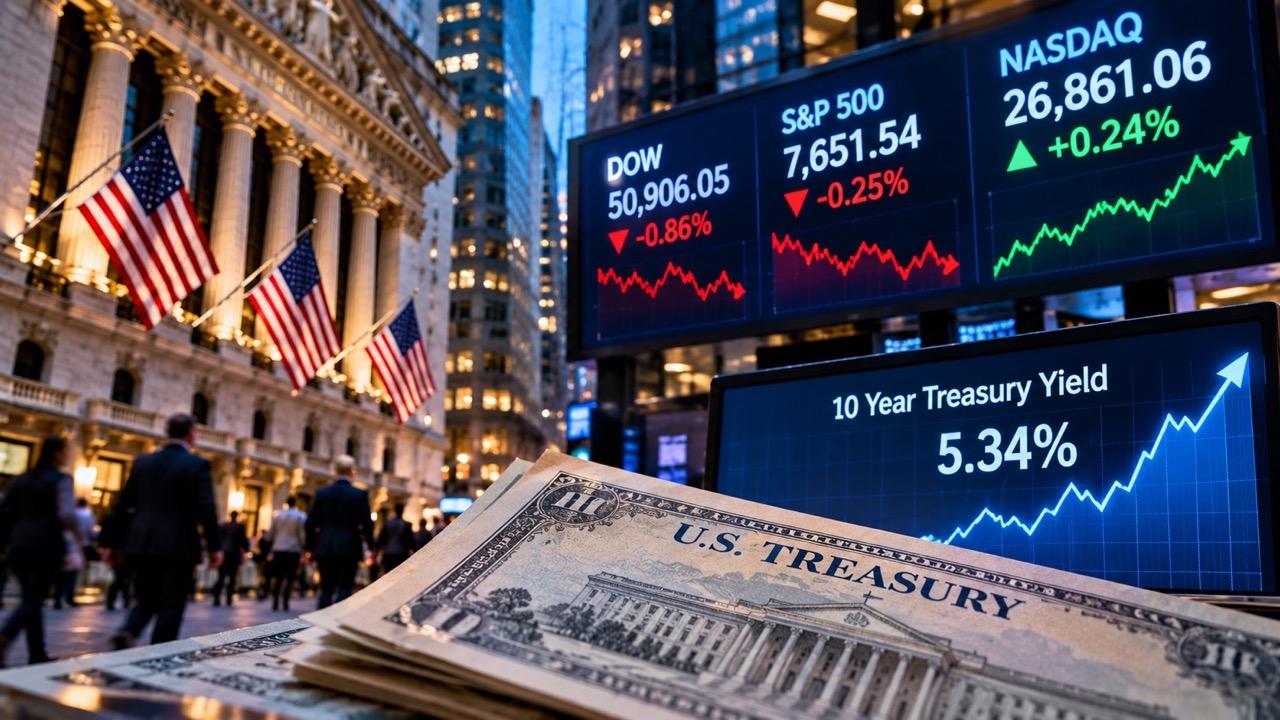
US stocks closed a volatile third quarter with a widening divide between technology shares and the broader market. The Dow Jones Industrial Average fell 0.86% on Sept. 30 to 50,906.05, while the S&P 500 declined 0.25% to 7,651.54. The Nasdaq Composite gained 0.24% to 26,861.06.
The final session of September highlighted the main tension heading into October: inflation data was softer than expected, but long-term Treasury yields continued climbing.
The Wall Street Journal noted that large technology companies helped keep the broader market afloat despite rising borrowing costs. The Nasdaq gained about 2.5% during the quarter, and the S&P 500 advanced about 2%, while the Dow lost 2.7%.
Treasury Yields Become the Key Market Pressure Point
The biggest concern entering the fourth quarter is no longer simply whether the Federal Reserve will raise rates. Investors are also confronting a sharp increase in long-term borrowing costs even as expectations for an immediate October rate hike have eased.
The benchmark 10-year US Treasury yield reached 5.34% on Oct. 1, its highest level since 2002, according to Reuters' latest Treasury-market report. The yield has risen sharply through the third quarter, producing the largest quarterly increase in more than two decades.
The 30-year Treasury yield also moved above 5.6%, extending a bond-market selloff that has pushed borrowing costs higher across the economy.
For equity investors, the move is significant because Treasury yields influence financing costs and the rates used to value future corporate earnings. The pressure has been particularly visible outside the largest technology companies. The equal-weighted S&P 500 fell 2.3% during the third quarter, according to the WSJ's quarter-end analysis, while the Russell 2000 dropped 7.5%.
AI Stocks Keep the Nasdaq More Resilient
Technology stocks have provided an important counterweight to the pressure from higher yields. The Nasdaq's quarterly gain came as major technology companies continued to benefit from spending on artificial intelligence infrastructure. Microsoft, Meta Platforms, Nvidia and Apple each posted gains of more than 10% during the third quarter, according to The Wall Street Journal.
Micron Technology's latest earnings report provided another data point for the AI investment cycle. The memory-chip maker reported record quarterly revenue and issued stronger-than-expected guidance, reinforcing demand expectations for memory used in AI systems.
Reuters reported that Micron's results supported semiconductor shares including Nvidia, Advanced Micro Devices and Applied Materials as investors assessed whether AI infrastructure spending can continue offsetting pressure from higher rates.
The broader economic data also presented a mixed picture. The August Personal Consumption Expenditures price index rose 3.4% from a year earlier, below the 3.7% estimate from economists surveyed by Reuters. At the same time, the final estimate for second-quarter US GDP was revised to a 2.2% annualized growth rate, supported by consumer spending and investment in AI infrastructure.
The combination leaves the Federal Reserve with conflicting signals: inflation has not returned to the central bank's 2% target, but the latest reading was softer than expected and therefore reduced immediate expectations for another rate increase.
Reuters reported that traders had reduced expectations for an October hike following the inflation data, although the possibility of another increase later in the year remains part of the market outlook. Oil remains another variable. Higher energy prices have contributed to inflation concerns, while continued geopolitical uncertainty involving the US and Iran has kept crude markets volatile. Reuters reported that Brent crude gained about 14% during September.
The Bloomberg market wrap likewise highlighted the interaction between rising bond yields, oil-market volatility and equity performance as investors moved into the final quarter.
For October, the market's central question is whether corporate earnings and AI investment can continue supporting stocks while Treasury yields remain elevated. The first quarter of the new earnings cycle, additional inflation data, and Federal Reserve communications will provide the next major tests.